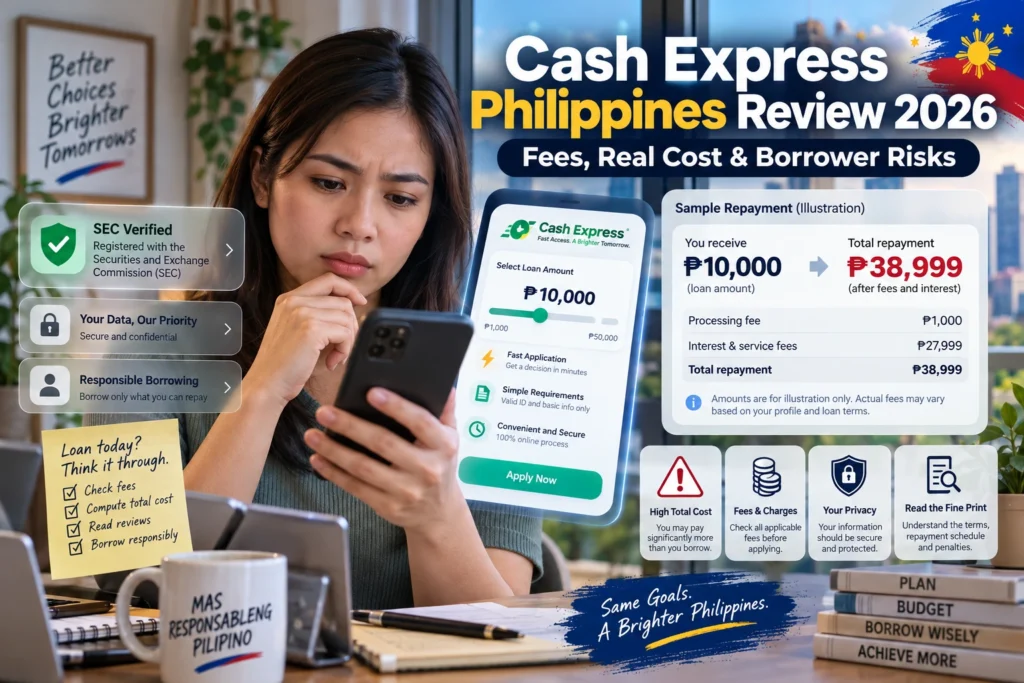
A quick-loan website can look straightforward until you try to answer the question that matters most: how much cash will you actually receive, and how much will you ultimately have to pay back? Cash Express Philippines publishes more pricing information than many online lenders, but its own pages also contain conflicting loan limits, terms, APR figures, and marketing claims that deserve careful reading before accepting an offer.
This review examines Cash Express Philippines using SEC records, the lender’s current disclosures and privacy policy, Philippine lending rules effective in 2026, official privacy guidance, repayment instructions, and recent borrower reports. We did not take out a Cash Express loan, so approval speed, actual offer size, collection activity, and individual repayment outcomes are not presented as first-hand findings.
Cash-Express Philippines Financing Inc. is an identifiable Philippine financing company appearing in SEC records under SEC Registration No. CS201951088 and Certificate of Authority No. 1309. Its predecessor’s CashXpress platform also appeared on the SEC’s recorded online-lending-platform list, and the old cashxpress.ph domain now redirects to cash-express.ph. The bigger borrower issue is cost: the current website publishes rates as high as 1.99% per day, a ₱1,000 issuance fee, and a representative ₱10,000 loan with ₱38,999 total repayment. Before accepting, compare the actual disclosure statement – not just the homepage – with the amount you will receive, every installment, and the total amount payable. (SEC Philippines)
| Borrower question | Current finding | Why it matters |
|---|---|---|
| Legal company | Cash-Express Philippines Financing Inc. appears in the SEC financing-company list under CS201951088 and CA No. 1309. (SEC Philippines) | Corporate registration alone is not enough; the CA is the more relevant authority to operate as a financing company. |
| Online platform history | The SEC’s 2021 recorded OLP list showed cashxpress.ph under the predecessor company; that URL now redirects to cash-express.ph. (SEC Philippines) | Verify the exact platform and company before sending documents or money. |
| Published loan amount | Current Cash Express pages conflict: some advertise up to ₱20,000, while the homepage mentions ₱30,000 and elsewhere ₱50,000. (Cash-express) | Treat the amount displayed in your actual offer as controlling, not a marketing maximum. |
| Published pricing | Homepage states 1.5% – 1.99% daily rates, up to 726.35% APR, plus a ₱1,000 issuance fee. (Cash-express) | The peso repayment can be far more informative than the advertised rate. |
| Representative example | ₱10,000 principal, 182 days, ₱27,999 interest, ₱1,000 issuance fee, ₱38,999 total repayment. (Cash-express) | Published borrowing cost is nearly three times the principal before considering any late charges. |
| Late payment | Cash Express states a 1% daily penalty on the loan amount plus ₱125 charges on specified overdue days. (Cash-express) | The applicable legal ceiling depends on the amount and actual tenor of the particular loan. |
| Payment posting | Some channels are listed as real time; bank and internet-banking payments may take 1 – 5 days. (Cash-express) | Paying on the due date through a slow channel can create posting risk. |
| Privacy | Policy covers ID, bank, biometric, income, credit and mobile-usage information and allows certain third-party processing. (Cash-express) | Read permissions and consent screens rather than assuming an NPC seal is an endorsement of every practice. |
Is Cash Express Philippines legitimate and properly authorized?
Cash-Express Philippines Financing Inc. is identifiable in official SEC records as a financing company with SEC Registration No. CS201951088 and Certificate of Authority No. 1309. That establishes an authorized corporate operator, but it does not by itself establish that every loan offer is inexpensive or appropriate for a particular borrower. (SEC Philippines)
Who operates Cash Express?
The current website identifies the operator as Cash-Express Philippines Financing Inc. under the business style and name Cash-Express, with an office at Unit 3101, Trade and Financial Tower, Bonifacio Global City, Taguig. It publishes SEC Registration No. CS201951088 and CA No. 1309. The SEC’s financing-company list as of August 31, 2024 independently contains the same registration number and CA. (Cash-express)
There is some corporate history behind those numbers. The SEC’s November 2021 online-platform list recorded Cashxpress South East Asia Lending Inc., the predecessor associated with registration number CS201951088, CA No. 2918 and cashxpress.ph. The present company operates as a financing company under CA No. 1309. (SEC Philippines)
That distinction matters because an old article or screenshot showing CA No. 2918 is not necessarily describing the company’s present licensing structure.
Is cash-express.ph the same platform as the older CashXpress site?
The old SEC-recorded URL, cashxpress.ph, currently redirects to cash-express.ph, providing a direct technical link between the legacy domain and the present website. (Cash-express)
I was able to verify the legacy platform through an official SEC list and the current financing-company authority separately. I did not find an accessible newer SEC primary-source list that literally displays the changed cash-express.ph spelling, so a borrower who wants maximum certainty should still check the SEC’s current recorded-OLP directory before submitting sensitive documents.
That is more precise than calling it simply an “SEC-approved app.” The SEC registers corporations, grants operating authority, and records online lending platforms under separate regulatory concepts.
How much can you actually borrow from Cash Express?
There is no single reliable maximum across Cash Express’s current public pages. Different pages advertise ₱20,000, ₱30,000 and ₱50,000 limits, while first-time promotional language refers to a maximum ₱10,000 offer. Your individual disclosure statement should therefore be treated as more important than the headline limit. (Cash-express)
This is one of the clearest transparency weaknesses in the public material.
The main homepage currently says:
- loan amount of ₱1,000 to ₱50,000;
- another section promotes “up to ₱30,000”;
- the peso-loan and application pages describe loans up to ₱20,000;
- first-time promotional language describes a maximum ₱10,000 amount during the introductory offer. (Cash-express)
The site also states that repeat customers may receive higher limits depending on credit history and previous repayment performance. It does not publish the complete scoring model. (Cash-express)
This means an applicant should not plan an emergency expense around the advertised maximum. An approved amount can be lower than the amount requested, something even testimonials published on Cash Express’s own website acknowledge. (Cash-express)
Who can apply, and what does Cash Express require?
Cash Express currently states that applicants should be Filipino residents aged 21 – 70, have employment or another stable source of income, an active mobile number, a personal bank account or e-wallet, and an accepted government ID. It also requests a selfie holding the ID. (Cash-express)
Accepted IDs listed by Cash Express include Passport, National ID, Driver’s License, SSS, UMID, Postal ID and PRC ID.
Its public eligibility rules do not establish separate published approval standards for salaried workers, freelancers, gig workers or self-employed applicants. The lender only states that employment or a stable income source is required. Therefore, claims that one employment category has a particular approval probability would be speculative.
Cash Express also says applications may be rejected at its discretion, and its current privacy disclosure indicates that credit assessment may use employment and income details, payment history, credit standing and certain mobile-usage information. (Cash-express)
What does a Cash Express loan really cost?
The lender’s own representative example is the clearest warning about cost: a ₱10,000 loan over 182 days is shown with ₱27,999 interest and a ₱1,000 issuance fee, producing total repayment of ₱38,999. The borrowing cost in that example is ₱28,999 before any late-payment charges. (Cash-express)
Interest, APR and the issuance fee
Cash Express currently publishes several pricing figures:
- 0% interest for the first seven days for qualifying new customers;
- 1.5% – 1.99% per day afterward or for returning customers;
- a stated maximum APR of 720% in one place and 726.35% elsewhere on the same page;
- a ₱1,000 issuance fee. (Cash-express)
The FAQ is less specific, saying that rates depend on the individual loan term and that an “additional fee or tax can be added,” instructing borrowers to read the loan agreement. (Cash-express)
That sits awkwardly beside promotional claims elsewhere on the site referring to “no hidden fees.” A borrower should therefore ignore broad marketing language and look for a peso-by-peso disclosure showing:
Amount borrowed → deductions → cash received → each scheduled payment → total interest → every fee → total repayment.
The ₱10,000 example in pesos
Cash Express gives this example:
| Item | Published amount |
|---|---|
| Principal | ₱10,000 |
| Term | 182 days |
| Interest | ₱27,999 |
| Issuance fee | ₱1,000 |
| Total repayment | ₱38,999 |
That means the published finance cost is ₱28,999 on a ₱10,000 principal, or roughly 290% of principal during the stated loan period. (Cash-express)
The webpage does not provide enough amortization detail to independently reproduce how the quoted daily rates generate exactly ₱27,999 of interest. For example, the answer depends on whether interest is calculated on original principal, declining principal, scheduled balances, or another contractual base.
That missing reconciliation is important. The disclosure statement attached to the actual offer should show the calculation much more clearly than a marketing page.
Do you really receive the whole approved amount?
The homepage calls the ₱1,000 charge an “issuance fee,” but the public example does not clearly say whether that amount is withheld from disbursement or simply added to repayment.
Therefore, it would be inaccurate to assume that a ₱10,000 approved loan automatically means only ₱9,000 reaches the borrower.
Check the actual “net proceeds” line before signing. If any fee is deducted before disbursement, the economic cost relative to cash actually received is higher than a calculation based only on approved principal.
Does the 2026 SEC interest-rate cap apply to Cash Express?
Sometimes it may; sometimes it may not. SEC Memorandum Circular No. 14, Series of 2025 applies from April 1, 2026 to unsecured general-purpose loans of no more than ₱10,000 with a tenor of no more than four months. Cash Express commonly advertises longer 180 – 365 day terms, which fall outside that specific definition. (SEC Philippines)
For loans covered by MC No. 14, the 2026 ceilings are:
- nominal interest: 6% per month;
- effective interest: 12% per month, including applicable fees but excluding late-payment penalties;
- late/nonpayment penalties: 5% per month on the outstanding scheduled amount due;
- total interest, fees, charges and penalties: not more than 100% of the amount borrowed. (RegAlert)
The scope is essential. These limits are not a universal interest cap on every Philippine loan.
Cash Express’s homepage says its standard loan duration is 180 – 365 days, but other pages use language referring to seven- or 14-day terms while still other sections describe those numbers as payment frequencies. (Cash-express)
So examine the actual contractual tenor, not a website label.
If Cash Express offers you, for example, an unsecured ₱5,000 loan whose actual maturity is within four months, MC No. 14 may be directly relevant. If the signed loan genuinely has a six-month tenor, the numerical MC No. 14 ceilings do not automatically apply merely because the principal is below ₱10,000.
Being outside that particular rate-cap rule does not remove other disclosure, consumer-protection, privacy and fair-collection obligations.
How fast are approval and disbursement?
Cash Express markets application decisions as taking roughly 5 – 30 minutes, while other parts of the site say processing or fund receipt can take up to 24 hours. These should be treated as advertised processing targets, not guaranteed borrower outcomes. (Cash-express)
The FAQ says the basic process is to apply online, get verified and approved, then receive funds in a personal bank account. The homepage also refers to e-wallet disbursement.
Factors such as ID verification, incorrect bank details, OTP issues and account information errors can create friction. Cash Express itself warns applicants to contact support if bank details were submitted incorrectly or if an OTP or email does not arrive. (Cash-express)
There is no public evidence allowing us to say that every qualified borrower receives money in 15 minutes.
How does repayment work?
Cash Express requires borrowers to generate a unique payment reference number. It lists GCash, Maya, GrabPay and 7-Eleven as real-time channels, while some bank and internet-banking payments may take one to five days to post. That posting delay matters close to a due date. (Cash-express)
Its repayment instructions list:
- GCash, Maya, GrabPay and 7-Eleven: real-time posting;
- Cebuana Lhuillier, Bayad Center, LBC, SM and Robinsons Bills Payment: about one day;
- banks: one to three days;
- internet banking: three to five days. (Cash-express)
The GCash instructions identify Dragon Loans as the biller. Borrowers should generate the reference number from their own Cash Express account rather than paying a bank or e-wallet account sent through an unsolicited message.
Cash Express also warns that it does not require advance processing or disbursement fees before a loan is released. (Cash-express)
A useful practical rule is to keep the transaction receipt and screenshot the account status after payment. If you use a slower channel, do not assume “paid today” means “posted today.”
What happens if you pay Cash Express late?
Cash Express states that late charges begin from the first day of delay and advertises a penalty of 1% of the loan amount per day, plus ₱125 charges on the 5th, 10th, 15th, 20th, 25th and 30th overdue days. Whether that formula is permissible depends partly on whether your specific loan falls within the 2026 capped-loan category. (cash-express.ph)
This is one reason the exact tenor matters so much.
For a loan covered by SEC MC No. 14, the late-payment ceiling is 5% per month on the outstanding scheduled due amount, and the total-cost cap is 100% of the amount borrowed. (RegAlert)
For loans outside MC No. 14’s defined scope, a borrower should not assume those numerical limits automatically govern the contract.
Cash Express also refers generally to maintaining a good credit record, but its accessible public material does not clearly document the exact timing or mechanics of reporting delinquent Cash Express accounts to the Credit Information Corporation. Borrowers concerned about reporting should ask the company directly for its current credit-reporting policy in writing rather than relying on assumptions.
How does Cash Express handle personal information?
The August 2026 Cash Express privacy policy covers a broad range of information, including government IDs, bank details, biometric data, employment and income information, payment history, credit standing and mobile-usage data. Philippine privacy rules nevertheless prohibit unnecessary, excessive and disproportionate processing. (Cash-express)
Cash Express states that its credit and identification assessment may involve:
- government identification numbers;
- photographs and other biometric information;
- employment and income details;
- financial and payment history;
- credit standing;
- mobile-usage information, including communication statistics;
- information from authorized partners such as credit bureaus, telecommunications providers and financial institutions. (Cash-express)
It also states that data may be subject to cross-border transfer and that certain service providers may receive the minimum data needed for assigned tasks. The policy provides mechanisms to request correction or deletion where legally applicable. (Cash-express)
Can Cash Express contact people in your phone?
For identity verification, Cash Express’s privacy policy says supplied personal references may be contacted. But that is not the same as permitting unrestricted debt collection through your address book. (Cash-express)
In March 2026, the NPC, SEC and DICT jointly reiterated that online lenders cannot engage in uncontrolled or disproportionate contact-list processing. For debt collection, persons in a borrower’s contact list other than properly designated guarantors must not be contacted merely to pressure the borrower. Character references and guarantors must also be treated differently.
The same advisory states that unnecessary app permissions are prohibited and that permissions should be revocable when their legitimate purpose has been completed.
An “NPC Registered” seal therefore should not be read as a blanket government endorsement of every data-processing or collection action. Borrowers still retain privacy rights.
What are borrowers saying about Cash Express in 2026?
Recent public feedback is mixed, but independent anecdotal discussions repeatedly raise two concerns: confusion over partial or minimum payments and balances rising quickly after missed payments. Those reports should be treated as individual experiences, not proof that every borrower receives the same terms or treatment.
A January 2026 r/utangPH discussion describes a borrower who believed two payments were reducing a ₱4,000 loan but was later told they were only minimum payments. A July – August 2026 thread includes a borrower seeking principal-only settlement after going overdue. An August post similarly describes confusion after making a partial payment offered within the system. (Reddit)
A September 2026 Reddit poster reported receiving a home visit and demand letter. That is a single unverified account and should not be treated as evidence that Cash Express routinely conducts field visits. (Reddit)
Third-party review pages also contain complaints about high charges and collection communications, while Cash Express’s own website publishes positive testimonials mentioning quick approval and helpful support. Neither source is statistically representative. (Ploan)
The recurring practical lesson is more useful than trying to turn anonymous reviews into a rating: if the payment screen offers “minimum,” “partial,” “extension,” or “prolongation,” ask in writing exactly how much of that payment reduces principal and what the balance will be afterward.
What are the main advantages and disadvantages?
Cash Express provides identifiable corporate information, publishes an illustrative high-cost example, documents several repayment channels and provides a current privacy policy. Its main weaknesses are high published borrowing costs and inconsistencies among its own pages regarding limits, terms, APR and product features.
| Potential advantage | Evidence-based limitation |
|---|---|
| Identifiable SEC-authorized financing company | Licensing does not imply that a particular loan is inexpensive. |
| Fully online application | Approval and advertised processing times are not guaranteed. |
| One government ID is prominently advertised | Application also involves a selfie and broader personal/financial information. |
| Multiple repayment channels | Some channels may take up to several days to post. |
| Pricing example is publicly visible | Example shows ₱38,999 repayment on ₱10,000 principal. |
| Privacy policy is detailed | Consent includes broad categories of financial, biometric and mobile-use data. |
| Repeat borrowing limits may rise | Higher access to credit can also increase exposure if repayment is already difficult. |
Who may find Cash Express relevant, and who should be especially cautious?
The product is most rational to evaluate only when the borrower knows the exact peso cost and already has a credible repayment source. Extra caution is warranted when paying the loan would require another loan, income is uncertain, or the disclosure statement is materially different from the website advertising.
Before proceeding, answer these questions using the actual offer – not the homepage:
- How much money will arrive in my bank account or e-wallet?
- Is any fee deducted before disbursement?
- What is the exact contractual tenor?
- How much is each scheduled payment?
- Does a “minimum” or “prolongation” payment reduce principal?
- What is the total peso repayment if I pay on time?
- What late-charge formula applies to my specific loan?
- Does the offer fall within the SEC’s ≤₱10,000 and ≤4-month 2026 capped-loan category?
- What phone, biometric and third-party data am I authorizing?
- Can I repay from normal income without taking another loan?
If the answer to the last question is no, approval speed is unlikely to solve the underlying cash-flow problem.
What should you verify immediately before accepting?
The final disclosure statement should override vague expectations created by advertisements. Do not confirm the electronic contract until the principal, net proceeds, fees, installment schedule, maturity date, late charges and total amount payable all make sense in pesos.
Save a copy of the disclosure statement and loan agreement before funds are released. Cash Express itself tells borrowers to read the loan agreement because additional fees or tax may apply. (Cash-express)
Also verify that you are dealing with the genuine operator. Cash Express publishes official contact channels and has issued warnings against accounts impersonating the company or requesting unauthorized advance payments. (Cash-express)
If collection behavior appears abusive, SEC guidance says complaints against registered financing and lending companies can be filed through the SEC iMessage portal. The March 2026 government advisory also directs unfair-debt-collection complaints to the SEC Financing and Lending Companies Department. (SEC Philippines)
FAQ
Is the first Cash Express loan really 0% interest?
Cash Express advertises 0% interest for the first seven days for qualifying new customers, but the same product can continue beyond that period at published daily rates. “0% for seven days” should therefore not be interpreted as meaning the whole loan is free. (Cash-express)
Can I take another Cash Express loan immediately after repayment?
Cash Express states that a customer in good standing may apply for another loan as early as the same day the previous balance is paid in full. Repeat limits are subject to credit history and previous repayment performance. (Cash-express)
Can I close my Cash Express account?
The current terms state that a user may terminate the relationship with seven business days’ written notice if no outstanding loan remains. The privacy policy separately provides rights to request correction or deletion of personal data where applicable, subject to legal retention requirements. (Cash-express)
What if my payment has not appeared yet?
First check the stated posting time for the channel used. Cash Express says some bank transactions can take one to five days. Keep the receipt and payment reference number and contact its payment-support channel if the payment remains unposted beyond the published period. (Cash-express)
A practical borrower decision framework
Cash Express Philippines has an identifiable financing-company operator, and its historical online platform can be traced through SEC records. That answers one part of the legitimacy question.
It does not answer the affordability question.
The lender’s own representative example – ₱10,000 principal and ₱38,999 total repayment over 182 days – shows why a borrower should start with total pesos rather than the phrase “fast loan.” The public website also contains enough conflicting figures on maximum amounts, terms and APR to make the signed disclosure statement particularly important.
Before accepting, verify five numbers on one page: cash you actually receive, total fees, every due date, total repayment if paid on time, and the balance that would result from any minimum or extension payment. Then check whether the actual tenor places the loan within the SEC’s 2026 capped-loan regime.
If those figures are unclear, obtain clarification in writing before authorizing the contract. If repayment depends on borrowing again, comparing another source of credit – or not taking the loan – deserves serious consideration.
How this review was researched
This review was prepared from the supplied evidence-first editorial brief, current Cash Express disclosures, accessible SEC records and issuances, official Philippine privacy guidance, repayment documentation and recent public borrower reports. No application or borrowing test was performed for this article.
References
- SEC List of Registered Financing Companies
Organization: Securities and Exchange Commission Philippines
Resource: List of Registered Financing Companies as of 31 August 2024
URL: SEC registered financing companies list - SEC Recorded Online Lending Platforms
Organization: Securities and Exchange Commission Philippines
Resource: List of Financing and Lending Companies Registered with the SEC and their Online Lending Platforms, updated 29 November 2021
URL: SEC recorded online lending platforms list - SEC Memorandum Circular No. 14, Series of 2025
Organization: Securities and Exchange Commission Philippines
Resource: Recalibrated Ceilings on Interest Rates and Other Fees Charged by Financing Companies and Lending Companies
URL: SEC MC No. 14, Series of 2025 - Cash Express Official Website
Organization: Cash-Express Philippines Financing Inc.
Resource: Current product terms, representative calculation, rates and company disclosures
URL: Cash Express Philippines official website - Cash Express Loan Application FAQ
Organization: Cash-Express Philippines Financing Inc.
Resource: Loan Application
URL: Cash Express loan application FAQ - Cash Express Repayment Instructions
Organization: Cash-Express Philippines Financing Inc.
Resource: How to Repay a Loan
URL: Cash Express repayment instructions - Cash Express Privacy Policy
Organization: Cash-Express Philippines Financing Inc.
Resource: Privacy Policy effective 4 August 2026, published within current website terms
URL: Cash Express privacy and terms disclosures - Public Advisory on Online Lending Platforms
Organization: Department of Information and Communications Technology, National Privacy Commission and Securities and Exchange Commission
Resource: Advisory on Online Lending Platforms, 18 March 2026
URL: 2026 government advisory on online lending platforms - SEC Complaints Guidance
Organization: Securities and Exchange Commission Philippines
Resource: Complaints – Financing and Lending Companies
URL: SEC complaints guidance - Recent Cash Express Borrower Discussions
Organization: Reddit / r/utangPH
Resource: Public borrower discussions concerning payments, overdue balances and collection experiences during 2026
URL: January 2026 discussion · July 2026 discussion · September 2026 discussion
Disclaimer:This article contains affiliate links. We may earn a small commission if you apply for a loan through our links, at no extra cost to you. The information provided is for educational purposes only and does not constitute professional financial advice. Please borrow responsibly.
Last Updated on September 22, 2026 by Elena Reyes
